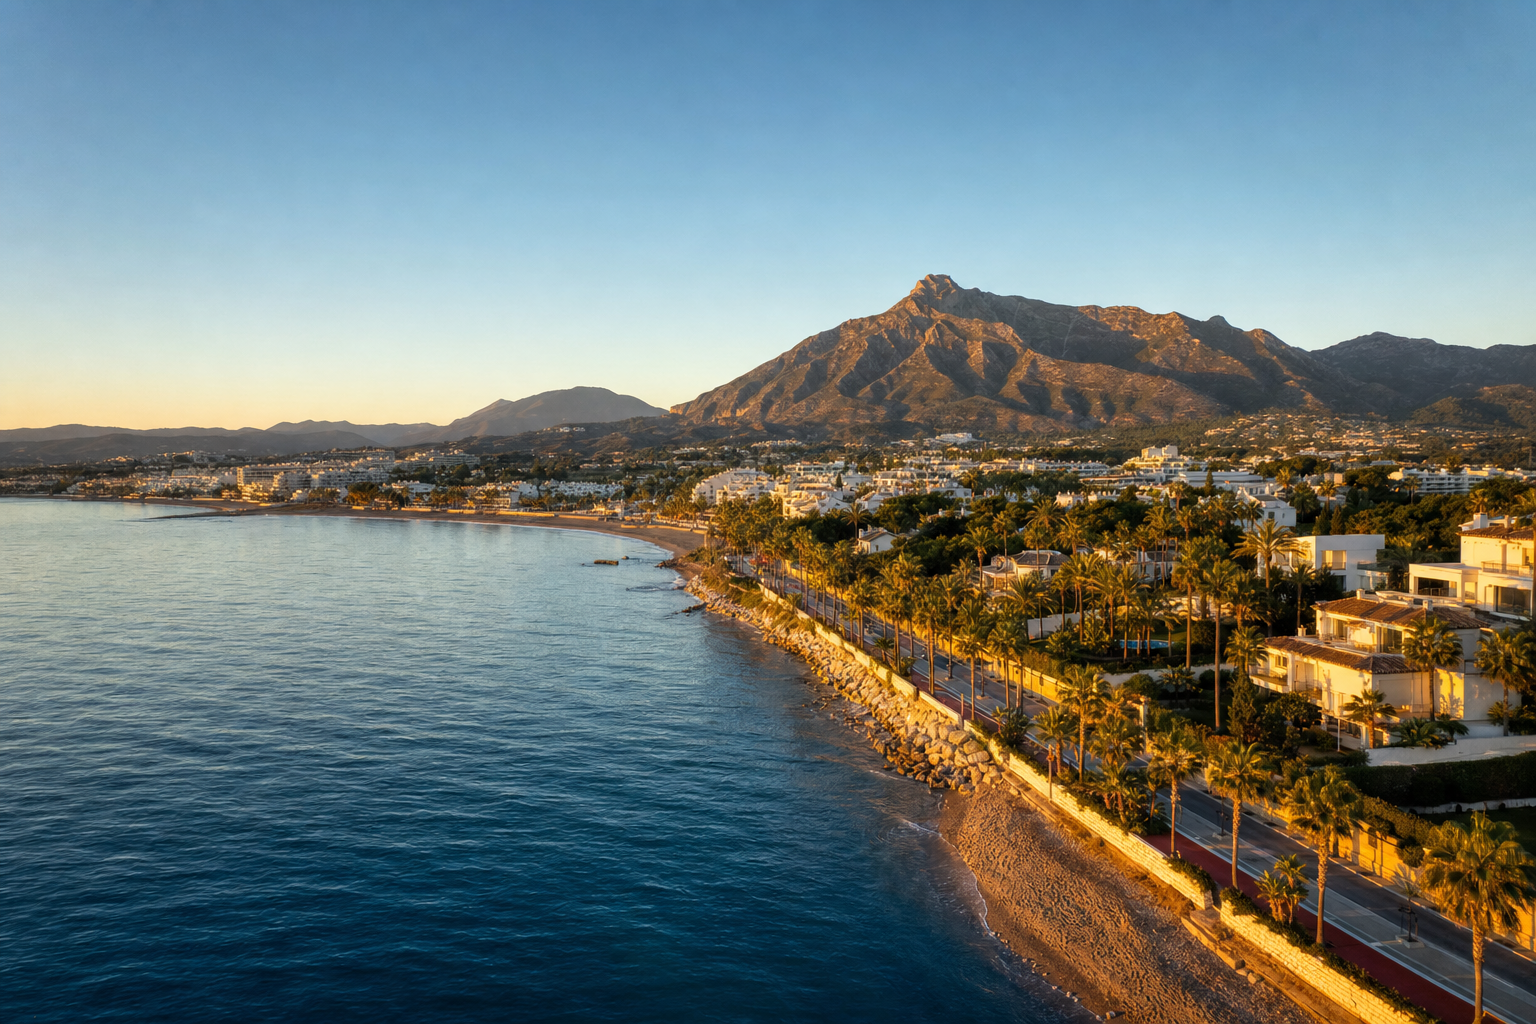
For a certain calibre of international buyer, the Costa del Sol has long sat somewhere between serious investment destination and aspirational lifestyle acquisition. Two things have changed around that question: the residency landscape, now that the Golden Visa has been abolished, and the off-plan pipeline, which is more legally demanding than a resale purchase.
This Costa del Sol luxury property investment guide is written for buyers who have already moved past the brochure stage. You will find where to read asking prices zone by zone, an honest account of why no rental yield can be quoted at the ultra-luxury tier, a clear-eyed analysis of off-plan versus resale risk, and a practical account of how non-EU investors approach ownership and residency after the abolition of Spain's Golden Visa. No invented statistics — just the information you need before you engage an agent or a lawyer.
Why Supply Is Constrained in the Trophy Zones of Marbella and the Costa del Sol
The short answer is structural scarcity. The trophy zones of the Costa del Sol — the Golden Mile, La Zagaleta, Sierra Blanca, the hillsides above Puerto Banús — are genuinely constrained. Land is finite, planning permissions remain restrictive within established urbanisations, and the most desirable plots do not come to market often.
Who is buying cannot be counted. No public dataset records buyer nationality at this price level. Any statement about a growing or shrinking national group is an observation from an agency's own enquiries, not a count.
On the supply side, land scarcity in premium zones, construction costs and lengthy planning processes limit how much new product reaches the top of the market. That is an argument about supply; it is not a measured return. No appreciation or year-on-year figure exists for these addresses: it would need closing prices at two dates, and Spain publishes none.
Luxury Micro-Market Breakdown — Character and Buyer Fit by Zone
Understanding the Costa del Sol as a single market is a category error. The difference in character and buyer profile between zones is substantial. What follows describes the zones; the figures are kept in one place. Current asking prices by zone, each with its sample size and date, are on the Marbella Property Index. The Marbella Property Index has measured the whole published register from €350,000 since 13 August 2026.
Marbella Golden Mile
The Golden Mile — the coastal strip running west from Marbella town toward Puerto Banús — remains the benchmark address on the Costa del Sol. Waterfront and first-line positions sit at the top of its asking range.
For investors, the Golden Mile is the address most widely recognised by renters and by future buyers. How fast a property there lets or resells cannot be put in a figure. No days-on-market figure is published: no public record shows when a listing sold.
Nueva Andalucía
Immediately behind Puerto Banús, Nueva Andalucía — often called the Golf Valley — has grown from a secondary market into one of the coast's established luxury zones.
The zone benefits from proximity to the marina without the noise, international school access, and a stock of contemporary new-build villas. Its upper end is trophy villas on elevated plots with Marbella skyline and sea views; ZD-VISO1, a seven-bedroom villa on the register, is an example.
Benahavís
The municipality of Benahavís encompasses La Zagaleta, El Madroñal, and the hillside urbanisations above the coast.
The zone is internally diverse. La Zagaleta, a gated estate of about 230 plots, sits at its top; El Madroñal offers comparable privacy and green-belt settings. The Marbella Property Index reports La Zagaleta and El Madroñal as zones of their own, separately from Benahavís.
Two eight-bedroom villas on the register show what the top of the Benahavís market looks like in scale and privacy: ZD-THH11 and ZD-CORQ; each page carries the current asking price. Browse the published register, or write to the desk about residences that are not published.
Estepona New Golden Mile
West of Marbella, the New Golden Mile — the coastal corridor between San Pedro and Estepona — is one of the coast's main new-build zones. It combines high-specification contemporary villas at the top with a wide band of apartments and townhouses below them, which is why an average and a median for the zone can sit far apart. For investors who want new-build product at a lower absolute price than the Golden Mile, this zone merits careful consideration.
Sotogrande
At the western edge of the Costa del Sol, Sotogrande retains a distinct character — equestrian, polo-oriented, and decidedly understated. It suits buyers who value privacy over proximity to Marbella's social infrastructure and who intend to hold for the long term.
Rental Income at the Luxury Tier — Why No Yield Figure Is Quoted
The yield figures quoted in generic Costa del Sol investment content are almost always blended averages that mix studio apartments in Fuengirola with beachfront villas in Marbella. They are not useful for investors operating at the luxury tier. No rental yield is published: no public dataset records achieved rents or closing prices for these homes. What an investor can assemble is the record of one property: its booked weeks, its rates and its costs.
At the ultra-luxury tier the rental model differs from mid-market product: a villa with a private pool, sea views and the service infrastructure that high-net-worth renters expect (concierge, chef, private driver referrals, event capability) is let by the week, to a small pool of renters, for part of the year.
Investors need to model income against realistic occupancy, not theoretical maximum weeks. The economic case is less about a yield rate and more about rental income partially offsetting holding costs, alongside the asset's use as a personal residence when it is not let.
One structural cost that investors often undermodel is the gap between gross rental income and net income after agency fees for managed luxury rental services, property management, insurance, maintenance, pool and garden care, and the costs associated with maintaining the property to the standard expected by renters paying premium rates. The cost of keeping a €5 million villa in rental-ready condition is not trivial. Investors should build a detailed annual ownership cost model before assessing any income — and should ask any agent presenting a rental income projection for the property-specific records behind it.
On the legal side: all short-term rental activity in Andalucía requires a Vivienda con Fines Turísticos (VFT) tourist licence, registered with the Junta de Andalucía. Applications require the property to meet specific habitability and safety standards. This is a manageable process for new-build properties with correct specifications, but can require investment in older properties. Factor the licence application timeline into your pre-purchase planning.
Off-Plan vs. Resale Luxury Property — Risk, Reward, and Developer Due Diligence on the Costa del Sol
The Costa del Sol has an active new-build pipeline at the luxury tier. Off-plan acquisition offers genuine advantages: a price fixed today for a product that will be delivered in eighteen to thirty-six months, and the option to customise specification. Whether the price moves between contract and completion cannot be known in advance. The New Golden Mile and parts of Benahavís hold much of the off-plan luxury supply.
But off-plan at the luxury tier carries specific risks that demand serious due diligence. These are the issues that matter most:
Stage payment structures and bank guarantees. Under Spanish law (historically governed by Ley 57/1968, now incorporated into the Ley de Ordenación de la Edificación), off-plan buyers are entitled to have their stage payments secured by bank guarantees or insurance. This means that if the developer fails to complete, you have a legal mechanism to recover your payments. In practice, not all developers make this easy to enforce, and not all buyers understand it. Before signing any off-plan contract, your Spanish property lawyer must verify that bank guarantees are in place for every stage payment — not just the initial reservation deposit.
Developer due diligence. Check the developer's track record: completed projects, litigation history, and the financial structure behind the specific development entity. Many developers in Spain operate via project-specific SPVs. The financial health of the parent group matters, but so does the capitalisation and debt structure of the development vehicle. Insist on audited accounts.
Licence and planning status. Ensure the development has a valid licencia de obras (building licence) before making any payment beyond a fully refundable reservation fee. An agreement signed before licences are in place creates uncertainty that is difficult and costly to unwind.
Resale advantages. For buyers who prefer to avoid construction risk entirely, the resale market at the luxury tier offers something the off-plan market cannot: certainty. You can see exactly what you are buying, negotiate based on condition and specifics rather than renders, and complete on a defined timeline.
The optimal choice between off-plan and resale depends on your timeline, risk tolerance, and whether you plan to customise the property. An adviser who knows both the specific developer and the zone is essential either way. Write to the desk to discuss which approach fits your objectives.
The Full Cost of Buying: Taxes, Fees, and Ongoing Ownership Costs Every Investor Must Model
One of the most consistent errors made by international buyers — including experienced ones — is underestimating the total cost of acquisition. In Andalucía, the transaction costs are material and must be factored into any return calculation from the outset.
Purchase taxes. For resale properties, the applicable tax is Impuesto de Transmisiones Patrimoniales (ITP). ITP on a resale in Andalusia is 7% of the price, or of the Catastro's reference value if that is higher (Article 41 of Andalusia's Ley 5/2021; Article 10.2 of the ITP-AJD law). For new-build properties (first transfer from developer), the applicable tax is IVA at 10%, plus Actos Jurídicos Documentados (AJD) stamp duty at 1.2% of the purchase price (11.2% together); a resale that pays ITP pays no AJD. The distinction between resale and new-build therefore has a direct impact on your tax exposure: at €5 million, the difference between ITP (7%) and IVA + AJD (11.2%) is €210,000.
Additional transaction costs. Budget for notary fees, Land Registry fees, and your lawyer's fees on top of purchase taxes. In the worked examples at €2–5 million — notary and land registry as estimated invoices, lawyer at 0.75% plus IVA — the total comes to 8.0–8.2% on top of the price for a resale and 12.2% for a new build. Only the tax is fixed by law; the other lines are estimates. The line-by-line examples are in our guide to Marbella property purchase costs.
Ongoing ownership costs. Annual costs for luxury property ownership include: Impuesto sobre Bienes Inmuebles (IBI, local property rates); community fees for urbanisation maintenance (which in gated communities such as La Zagaleta can be substantial); insurance; property management; and the non-resident income tax (IRNR) obligation for non-resident owners who do not let their property — Spain imputes a notional rental income even on unoccupied properties, taxed at rates that vary by tax residency.
Wealth tax (Impuesto sobre el Patrimonio). Andalusia gives 100% relief on wealth tax (Article 25 bis of Ley 5/2021). While the state Temporary Solidarity Tax on Large Fortunes (ITSGF) is in force, that relief is limited to the difference between the two bills, so above the threshold the taxpayer pays what the solidarity tax would charge. Nothing is due while net wealth after the €700,000 allowance stays within €3,000,000; above that the scale is 1.7% to €5,347,998.03, 2.1% to €10,695,996.06 and 3.5% beyond (Article 3 of Ley 38/2022). Non-residents have the same €700,000 allowance and are assessed on their Spanish assets only (Article 28.Tres of Ley 19/1991). On €5,000,000 of net Spanish assets with no debt: €5,000,000 − €700,000 = €4,300,000; the first €3,000,000 at 0% and the next €1,300,000 at 1.7% — €22,100 a year. Any buyer at the €5 million+ level should obtain detailed advice on their specific exposure from a Spanish tax specialist before committing to a purchase.
Inheritance tax. Andalucía has largely bonified (reduced) inheritance tax for close relatives who are Spanish tax residents. For non-residents inheriting Spanish property, the position is more complex and the tax can be significant. Corporate ownership structures — specifically a Spanish Sociedad Limitada (SL) holding company — are used by sophisticated investors to manage succession planning and create a cleaner transaction structure at exit; holding through a company does not by itself take the property out of wealth tax. This is standard practice among institutional and family-office buyers in this market. Whether it is appropriate for your situation depends entirely on your residence, tax treaty position, and estate planning objectives — this is not a decision to make without specialist advice.
Residency and Tax Optimisation After Spain's Golden Visa — Structuring Your Investment as a Non-EU Buyer
Spain's investor residence visa (the Golden Visa) — every route, not only property — was abolished by Ley Orgánica 1/2025 of 2 January (final provision 21), in force since 3 April 2025. Buying property gives no right of residence at any price. Applications filed before that date are decided under the old rules, and permits already granted keep their validity and can be renewed under them. For buyers who were considering the Golden Visa as part of their investment rationale, this is a significant change that requires alternative planning.
Two residency pathways are now most relevant for non-EU buyers acquiring property on the Costa del Sol:
Non-Lucrative Visa (NLV). This visa allows non-EU nationals to reside in Spain without working, provided they can demonstrate sufficient financial means to support themselves and any dependants (the income threshold is set annually by the Spanish government; obtain current figures from an immigration lawyer). It does not require a property investment of any minimum value, but owning a property in Spain is typically presented as evidence of accommodation. For buyers who wish to spend significant time in Spain — six months or more annually — and do not need to generate income from Spanish sources, the NLV is the most straightforward pathway. Crucially, spending more than 183 days per year in Spain makes you a Spanish tax resident, which has profound implications for your worldwide income tax position.
Digital Nomad Visa. For buyers who work remotely for non-Spanish employers or clients, the Digital Nomad Visa (introduced in 2023 under Spain's Startups Act) offers an attractive route. It permits income from remote work and, critically, allows access to the Beckham Law (régimen especial de trabajadores desplazados) flat rate income tax regime under certain conditions. For high-earning professionals relocating to Spain for a defined period, this can be a very effective structure. Again, specialist immigration and tax advice is essential before applying.
For buyers who do not intend to reside in Spain and are acquiring purely as an investment or lifestyle asset, the residency question may be secondary — but the tax implications of non-resident ownership (IRNR, wealth tax, inheritance) remain live issues that demand professional structuring.
The desk introduces buyers to independent lawyers, tax advisers and banks; the buyer chooses, instructs and pays them directly.
Sustainability and Smart-Home Specification — Why the Energy Rating Matters
This is an area almost entirely absent from general Costa del Sol investment commentary, yet it is increasingly material to both letting and resale at the luxury tier.
In Spain, all properties offered for sale or rent must have an Energy Performance Certificate (Certificado de Eficiencia Energética). The rating runs from A (most efficient) to G (least). New-build luxury developments on the Costa del Sol are increasingly being designed and certified to A or A+ standards, and a small but growing number of developers are pursuing Passivhaus certification — a building standard that delivers near-zero energy demand through insulation, airtightness, and heat recovery ventilation.
The investment relevance is twofold. First, many international buyers come from markets where smart-home integration and energy efficiency are baseline expectations, not premium features, and a villa with a dated EPC rating and no building management system is a harder sell to them. Second, the EU's energy performance regulations are tightening, and properties at the bottom of the EPC scale face increasing friction at the point of resale — both in terms of buyer negotiating leverage and, potentially, future regulatory compliance costs.
For investors acquiring for rental income, an A-rated property with solar generation, battery storage, and smart-home control is more attractive to the high-net-worth renter than one with outdated infrastructure. No public dataset measures the size of the premium: it would need matched closing prices, and Spain publishes none. For new-build off-plan acquisitions, insisting on the highest achievable EPC rating and a documented smart-home specification is simply good practice.
The Step-by-Step Luxury Acquisition Process — From Search to Notary, What to Expect in Marbella
The Spanish property acquisition process is well-established and, when properly managed, straightforward. What follows is a clear account of each stage as it applies to a luxury purchase on the Costa del Sol.
1. NIE number. Every buyer — including non-EU nationals — must obtain a Número de Identificación de Extranjero (NIE) before completing a Spanish property purchase. This is a Spanish tax identification number. It can be obtained in Spain at a police station (Comisaría), or via a Spanish consulate in your home country. Your lawyer can also obtain it via power of attorney. Allow two to six weeks, depending on the police station or consulate and on whether a lawyer applies under a power of attorney.
2. Spanish bank account. While not legally mandatory in all cases, having a Spanish bank account significantly simplifies the transfer of purchase funds and payment of ongoing taxes. Open this in parallel with the NIE process.
3. Property search. Some residences are not published and are shown by introduction. Browse the published register, describe the brief to Ask Muse, the AI search on this site, or write to the desk about residences that are not published.
4. Reservation contract (Contrato de Reserva). Once a property is agreed in principle, a reservation contract is signed and a small reservation deposit paid to take the property off the market while due diligence is completed. This sum is deducted from the purchase price at completion.
5. Legal due diligence. Your lawyer will verify title, check for encumbrances, outstanding debts, unpaid IBI or community charges, confirm planning legality of all structures, and review the nota simple (Land Registry extract). At this stage for off-plan purchases, bank guarantees must also be verified. This step is not optional and not a formality — it is the most important thing your lawyer does.
6. Private purchase contract (Contrato de Arras). The arras contract formalises the agreed price and terms and requires the buyer to pay 10% of the purchase price. If the buyer withdraws, this sum is forfeited. If the vendor withdraws, they must return double the deposit. This is a serious financial commitment: enter it only once your due diligence is complete.
7. Mortgage (if applicable). Non-resident buyers can access Spanish mortgage financing. Loan-to-value is not set by law. Spanish banks commonly lend non-residents up to 60–70% of the lower of price and valuation; the figure, the rate and the fees are the bank's own offer — get it in writing. Spanish banks will require their own valuation (tasación). Mortgage approval should be secured before the arras stage.
8. Completion (Escritura de Compraventa). Completion takes place before a Spanish notary. Both parties (or their power-of-attorney representatives) sign the escritura — the formal deed of sale. The balance of the purchase price is paid, the notary verifies the transaction, and ownership transfers. The escritura is then registered at the Land Registry.
9. Post-completion. ITP on a resale, or AJD on a new build, is self-assessed on Modelo 600 and paid to the Junta de Andalucía within two months, counted from the day after the deed is signed (Article 69 of Ley 5/2021). Register the property in your name at the Land Registry (your lawyer handles this). Notify the town hall (catastro) of the change of ownership. Set up direct debits for IBI and community fees.
A cash purchase typically takes two to three months from reservation to deed; longer with a mortgage. An off-plan purchase runs to the developer's construction programme. Having an experienced Spanish property lawyer — independent of your agent — is non-negotiable at every stage.
Which Zone Fits Which Buyer
The desk does not forecast. What can be set out is which zone suits which brief, with the prices left to the Marbella Property Index, where each zone's asking median stands with its sample size and date.
For address recognition: The Golden Mile remains the benchmark, recognised by the broadest international buyer pool.
For contemporary villas near golf and Puerto Banús: Nueva Andalucía — large contemporary villas with views, golf proximity, and access to the social infrastructure of Puerto Banús; ZD-VISO1 shows the top of what the zone offers.
For ultra-privacy and estate-scale acquisition: Benahavís — and La Zagaleta in particular — for buyers to whom compound security and setting are primary considerations; ZD-THH11 and ZD-CORQ are examples on the register.
For new build at a lower absolute entry point: The Estepona New Golden Mile, for buyers who want a contemporary, energy-efficient villa.
Any purchase is exposed to the same uncertainties as any luxury real estate market: interest rates, geopolitical events affecting buyer travel and capital flows, and regulatory changes affecting short-term rental licensing. None of them can be forecast here, and no well-structured investment decision ignores them.
For current asking prices across all zones, visit the Marbella Property Index. To discuss your specific objectives, write to the desk.