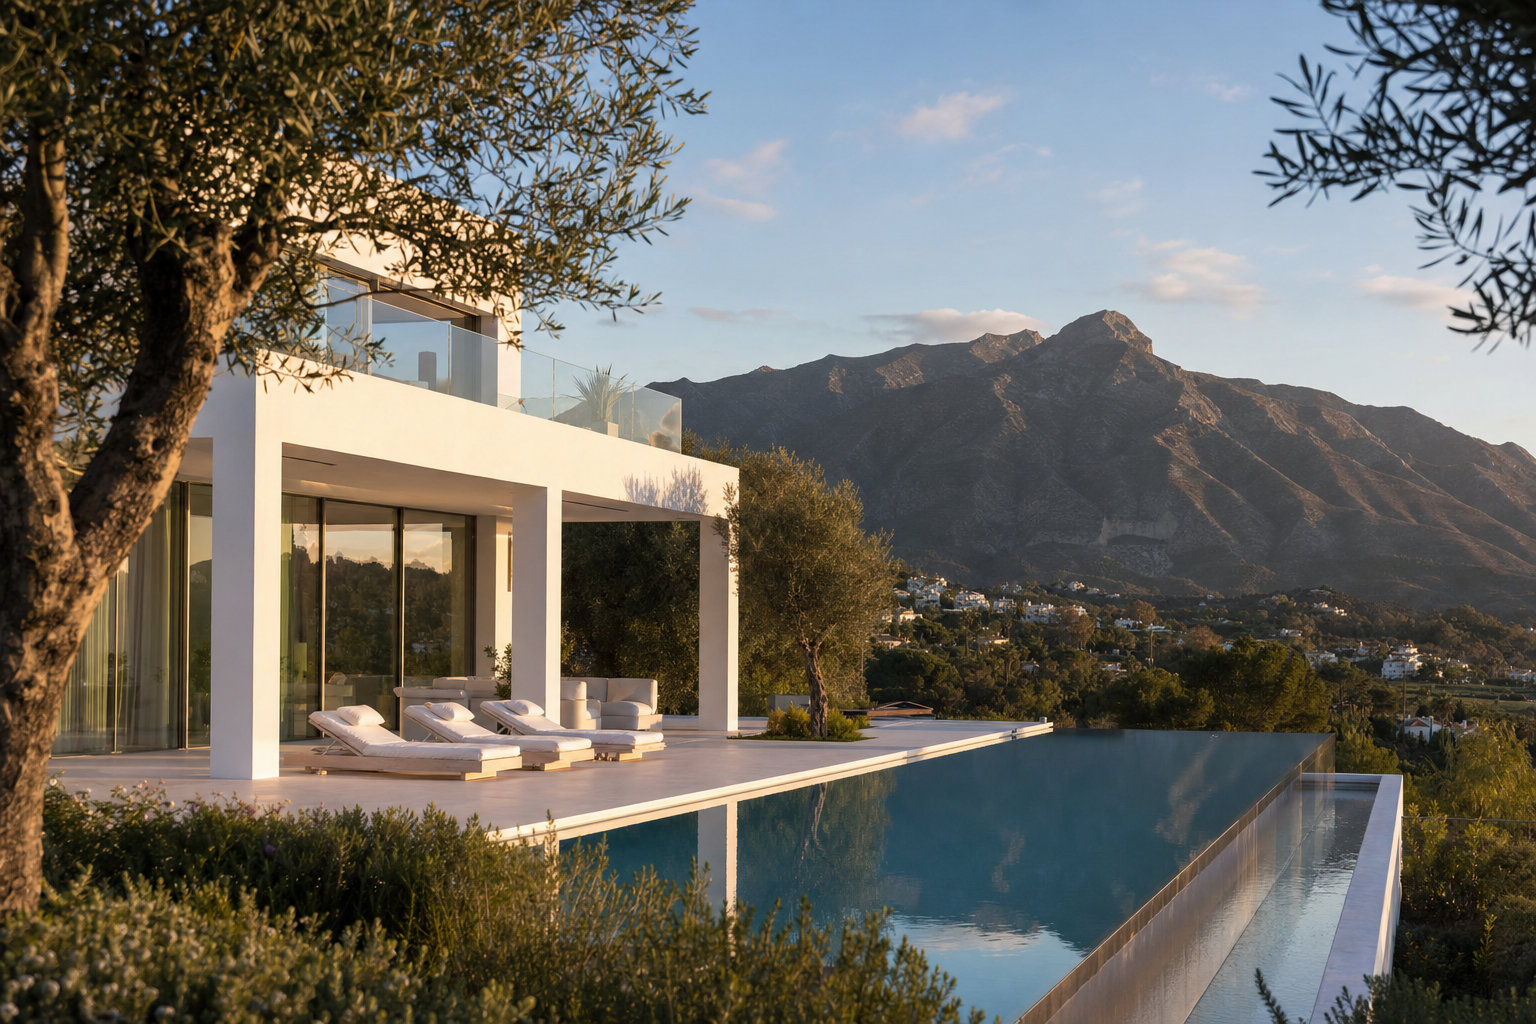
Serious buyers do not shortlist a development because of a sunset render. They shortlist it because they understand which micro-market aligns with their lifestyle priorities, what the acquisition costs will total on completion day, and how they have verified the developer's ability to deliver. This Marbella new build developments guide is written for that kind of buyer: one who wants the full picture before committing capital — not a curated mood board.
What follows covers the zones, the taxes and the checks. Current asking prices by zone, each with its sample size and date, are on the Marbella Property Index.
What Can and Cannot Be Measured About Marbella's New Build Market
The structural case for Marbella new build is not complicated, but it is frequently overstated with invented numbers. Here is what can actually be measured.
Current asking prices by zone, each with its sample size and date, are on the Marbella Property Index. The Marbella Property Index has measured the whole published register from €350,000 since 13 August 2026. The aggregate matters less than the divergence by zone, which is where decisions should be made.
The demand side cannot be counted. No public dataset records buyer nationality at this price level. The supply side can be described: buildable land in premium locations is genuinely scarce. Golden Mile addresses, Sierra Blanca ridge positions, and front-line golf plots in Nueva Andalucía simply cannot be manufactured again.
Where land is scarcest, new build is rarest. Areas with more land availability — Benahavís and the Estepona New Golden Mile — hold more of the new-build supply.
The practical difference between new build and resale is straightforward: new build is taxed more heavily at purchase (see the cost section below), and delivers a ten-year structural warranty (garantía decenal) and modern energy-performance standards (mandatory EPC ratings that resale stock increasingly struggles to meet). Whether its price moves between reservation and completion cannot be known in advance.
The Six Micro-Markets Explained — Which Zone Matches Your Buyer Profile
Generic "sea views and golf nearby" descriptions help no one. What follows maps each principal zone to the buyer profile it genuinely suits; the current asking median for each is on the Marbella Property Index.
Golden Mile: The Established Address
The Golden Mile — the coastal corridor running roughly from Marbella town westward toward Puerto Banús — remains the single most recognised address on the Costa del Sol. New build supply here is limited; when a development does come to market, it tends to be boutique in scale.
Who it suits: Buyers for whom address recognition matters — those who will use the property seasonally, want proximity to Marbella town's restaurants and beach clubs, and have no particular need for privacy beyond a gated perimeter. The Golden Mile is the logical choice for a buyer who wants an asset that is immediately understood by any peer they mention it to.
Sierra Blanca / La Zagaleta: Privacy-First UHNW
Sierra Blanca, rising above the Golden Mile, and La Zagaleta, the private estate in the hills above Benahavís, are not zones you stumble across: both are gated. La Zagaleta sits within the Benahavís municipality; the Marbella Property Index reports each as a zone of its own.
Who it suits: Ultra-high-net-worth families requiring genuine privacy, security infrastructure (24-hour perimeter patrol, restricted vehicle access), and the kind of plot scale — multiple thousands of square metres — that allows for compound-style living. The buyer here is not looking for footfall; they are looking for exclusion from it.
A representative listing in this tier: an 8-bedroom villa in Benahavís on the register, whose scale and specification reflect the kind of architecture that defines this micro-market.
Nueva Andalucía Golf Valley: The Investor-Relocator Hybrid
Nueva Andalucía is the most analytically interesting zone for new build buyers precisely because it serves multiple profiles simultaneously. It hosts Aloha Golf, Las Brisas, and Los Naranjos — three of the Costa del Sol's most respected courses — within a dense residential fabric of villas, townhouses, and apartment developments at varying price points.
Who it suits: The golfer-relocator who wants walkable access to courses without sacrificing proximity to Puerto Banús (five minutes by car). Also well-suited to the buyer seeking new build apartments or villas to let, since golf draws visitors outside the summer peak. A 7-bedroom villa in Nueva Andalucía on the register illustrates the top of what the zone produces — architecture designed for a buyer who wants both golf-valley character and compound-grade specification.
Puerto Banús: Lifestyle Premium, Investment Calculation Required
Puerto Banús is a lifestyle destination with a mature property stock. New build here tends to be apartment-dominant; villa land is extremely scarce. Buyers attracted to Puerto Banús primarily for rental income should model carefully: management costs in a resort-style building reduce net income more than the brochure implies.
Who it suits: Lifestyle-led buyers and those seeking an established, recognisable brand address with easy marina access.
San Pedro de Alcántara / Guadalmina: Growing Infrastructure
San Pedro sits between Puerto Banús and Guadalmina. Infrastructure investment — the reconfigured seafront promenade, improved road connections — has been steadily improving the zone's liveability.
Who it suits: Buyers who want new build quality and are comfortable with a slightly less "prime" address than the Golden Mile or Nueva Andalucía.
Marbella East: Quieter, Greener, Less Dense
Marbella East — covering areas such as Elviria, Cabopino, and Las Chapas — is quieter and more verdant than the western corridor. New build supply in this corridor is less abundant.
Who it suits: Buyers seeking quieter, more verdant surroundings, less urban density, and the kind of east-facing morning light and pine-forest setting that the western corridor cannot replicate.
Branded Residences vs. Premium Boutique Developments — What the Price Premium Actually Buys You
Branded residences on the Costa del Sol — developments operating under fashion house or luxury hotel flags — have attracted significant attention, and for understandable reasons. The proposition is coherent: a globally recognised brand name attached to a property addresses some of the uncertainty that buyers face when purchasing from an unknown developer in an unfamiliar market.
The practical question is what the brand premium buys in financial terms, and where the trade-offs lie.
What the premium delivers: - Management infrastructure. Branded developments typically include a concierge, maintenance, and property management tier that operates to a defined service standard. For buyers who will use the property seasonally and need reliable hands-off management, this has genuine value. - International recognisability. A branded residence is more immediately legible to a global buyer pool on resale — particularly relevant for buyers whose exit may target markets (Asia, the Gulf) where the Marbella micro-market is less intimately known but the brand name is universally understood. - Specification floor. Brand approval processes typically enforce minimum specification standards that protect buyers from developer cost-cutting in finishes and systems.
Where the trade-offs appear: - Higher purchase price. The brand premium is real and paid at the point of acquisition, not recovered automatically. - Service charge exposure. Branded management structures carry higher annual community and service fees than comparable non-branded developments. Buyers must model net returns after these deductions. - Less customisation latitude. Brand standards often limit the degree to which individual buyers can modify layouts or finishes — a significant constraint for buyers with specific requirements (see the customisation section below).
Non-branded trophy developments, by contrast, offer the buyer more direct negotiating power with the developer, greater flexibility on specification upgrades, and — if the developer is well-chosen — equivalent or superior build quality without the annual overhead of a management brand. The risk is higher developer dependency, which is precisely why vetting (see the due diligence section below) matters more in this category.
An eight-bedroom villa in Benahavís on the register is an example of an unbranded trophy development, where the case rests on architecture, land position, and developer execution rather than a fashion house endorsement.
The Complete Cost of Buying a New Build in Marbella — No Surprises
One of the most consistent surprises for first-time buyers in Spain is the gap between the headline price and the total funds required on completion day. This section covers every component.
Purchase Taxes
For a new build (primera transmisión — first transfer from developer to buyer), the applicable tax is IVA at 10%, applied to the purchase price. This is the same rate whether the property is an apartment or a villa, coastal or inland. It is also the same whoever the buyer is — an individual or a company (Article 91.Uno.1.7.º of the VAT law, Ley 37/1992) — and it is paid to the developer with the price.
In addition, AJD (Actos Jurídicos Documentados — stamp duty) applies at 1.2% in Andalucía on new build transactions. This is levied on the same value as IVA.
For context: a resale property in Andalucía attracts ITP (Impuesto de Transmisiones Patrimoniales) at 7% instead of IVA+AJD. New build is therefore more expensive in tax terms than resale — 11.2% against 7% — a fact that should be reflected in any net return calculation.
Legal and Notary Costs
Independent legal representation is not optional in any transaction a serious buyer would consider — it is essential. A lawyer's fee is agreed, not regulated: commonly 0.5–1% of the price plus 21% IVA. The worked examples on this site assume 0.75% plus IVA. Notary and land-registry fees are statutory tariffs (Real Decreto 1426/1989 and Real Decreto 1427/1989), not percentages of the price. The figures on this site are estimates of the final invoices, not the tariff itself. In the worked examples at €2–5 million — notary and land registry as estimated invoices, lawyer at 0.75% plus IVA — the total comes to 8.0–8.2% on top of the price for a resale and 12.2% for a new build. Only the tax is fixed by law; the other lines are estimates. The line-by-line examples are in our guide to Marbella property purchase costs.
NIE and Administrative Costs
All foreign buyers require a NIE (Número de Identificación de Extranjero) — a Spanish tax identification number — before signing any purchase deed. This is a procedural requirement, obtainable through a Spanish consulate in your country of residence or in-country with a lawyer's assistance. Allow sufficient lead time; consulate appointment availability varies by country.
Community Fees and Ongoing Costs
New build developments — particularly those with concierge services, pools, gardens, and 24-hour security — carry annual community fees (gastos de comunidad) that can range widely depending on the service level provided. In a premium development with full amenity provision, these fees are a material cost of ownership. Request the projected fee schedule from the developer before signing, not after.
Currency Risk for Non-Euro Buyers
For buyers whose primary currency is sterling, dollars, or dirhams, the period between reservation deposit and completion represents meaningful foreign exchange exposure. On a €5 million purchase, a 5% adverse currency move costs €250,000 in home-currency terms. Specialist FX brokers offer forward contracts and rate hedging instruments that are worth engaging well before completion. This is not a speculative step; it is risk management.
The Golden Visa — A Note
Spain's investor residence visa (the Golden Visa) — every route, not only property — was abolished by Ley Orgánica 1/2025 of 2 January (final provision 21), in force since 3 April 2025. Buying property gives no right of residence at any price. Applications filed before that date are decided under the old rules, and permits already granted keep their validity and can be renewed under them. Buyers whose residency strategy depended on this route should seek legal advice on alternative pathways.
How to Vet a Developer Before You Sign — A Due Diligence Checklist
The most consequential decision in any off-plan purchase is not which unit to choose — it is which developer to trust. The following checklist covers the minimum verification any informed buyer should complete.
1. Verify the Building Licence (Licencia de Obras)
A valid licencia de obras from the relevant town hall (Marbella, Benahavís, or Estepona, depending on the plot's municipality) is the first prerequisite. No legitimate developer should resist providing a copy. If a project is marketed before the licence is granted, understand that any reservation deposit is held against a condition that has not yet been satisfied — and model your reservation agreement accordingly.
2. Confirm the Bank Guarantee (Aval Bancario)
Spanish law requires developers to protect all stage payments made by buyers under a bank guarantee or insurance policy. This means that if a developer enters insolvency before completion, buyers are entitled to recover their deposits. However, the guarantee only protects you if it has actually been issued and if your deposit has been paid into a segregated client account linked to that guarantee. Your lawyer should verify both before any funds are transferred.
3. Assess the Developer's Track Record
Request a list of previously completed developments with addresses. Visit at least one completed project if at all possible — not to evaluate aesthetics but to inspect build quality, speak to existing residents about the completion process, and verify whether the developer delivered on time and to specification. Delays and specification changes on previous projects are the most reliable predictors of the same on your project.
4. Review the Developer's Financial Standing
A solvent developer has a properly capitalised corporate structure, a lending bank willing to finance the construction, and — in most cases — a minimum pre-sale threshold before construction commences. Ask which bank holds the construction finance facility. A reputable Spanish bank's willingness to lend against a specific project is an imperfect but meaningful signal of the project's viability.
5. Read the Purchase Contract Before Engaging Enthusiasm
The reservation contract (contrato de reserva) and the private purchase agreement (contrato privado de compraventa — typically a ten-percent arras agreement) are the documents that define your rights in every scenario: delay, insolvency, specification change, and completion. Have your lawyer review both before you sign anything and before you pay any deposit. The cost of this review is trivial relative to what it protects.
Customisation Windows — How to Personalise Your Off-Plan Property Before It's Too Late
One of the genuine advantages of buying off-plan — and one of the most frequently mismanaged — is the ability to customise the property to your requirements. The window for meaningful changes is determined entirely by where the project sits in its construction programme, and it closes faster than most buyers expect.
Pre-Foundation: Maximum Flexibility
If you reserve before the foundation slab is poured, the range of possible modifications is broad: structural layout changes (merging rooms, repositioning staircases, expanding terraces), installation of smart-home infrastructure (control systems, integrated audio-visual, enhanced security), specification of bespoke kitchen and bathroom packages, and additions such as wine cellars, home-cinema rooms, or dedicated staff accommodation. This is the stage at which the developer is most financially motivated to accommodate requests, and the construction programme has not yet locked in decisions.
Structure Complete, Fit-Out Pending: Moderate Flexibility
Once the shell structure is complete, layout changes become expensive or impossible, but finish selections (flooring, tiling, kitchen cabinetry, bathroom suites, sanitary ware) remain fully negotiable. Mechanical and electrical upgrades — underfloor heating extensions, EV charging provision, additional air-handling capacity — are still achievable at this stage, though at higher cost than if specified earlier. Home-automation upgrades can typically still be integrated before plastering and secondary electrics are installed.
Fit-Out Progressing: Limited Flexibility
Once the fit-out is materially advanced, the scope for change narrows to surface finishes and appliance selections in most cases. Structural and systems changes at this stage carry disproportionate costs and risk disrupting the construction programme — the developer is entitled to decline them.
Practical advice: Make your upgrade list at reservation, get every agreed change in writing as a signed addendum to the purchase contract, and confirm the price of each upgrade explicitly. Verbal agreements at the sales office do not survive construction; written addenda do.
Off-Plan Payment Structures, Staged Schedules and Financing for International Buyers
Typical Staged Payment Structure
The most common off-plan payment structure in the Marbella new build market follows a broadly consistent pattern, though developers vary in their specific staging:
- Reservation deposit: A small fixed sum paid on reservation, typically non-refundable if the buyer withdraws without cause.
- Private purchase agreement (arras/contrato privado): A further payment bringing the total deposit to approximately 10% of the purchase price, payable on signing of the private purchase agreement — usually within 30 days of reservation.
- Stage payments during construction: A series of tranches (varying by developer, but commonly three to four payments) payable at defined construction milestones — typically foundation completion, structure completion, and roof/enclosure.
- Balance on completion: The remaining purchase price, paid at the notary on signature of the escritura (title deed), typically accompanied by the simultaneous drawdown of any mortgage.
Spanish Mortgages for Non-Residents
Non-resident buyers can access Spanish mortgage finance, though on different terms than resident buyers. Loan-to-value is not set by law. Spanish banks commonly lend non-residents up to 60–70% of the lower of price and valuation; the figure, the rate and the fees are the bank's own offer — get it in writing. Banks require proof of income and existing asset base, and will conduct their own valuation (tasación), which may differ from the agreed purchase price. The application process should be initiated well in advance of any anticipated completion date; Spanish bank processing timelines can be lengthy.
International private banks and wealth managers familiar with the Marbella market can sometimes offer more flexible financing structures for UHNW buyers — worth exploring in parallel with the Spanish banking route.
Currency Hedging for Stage Payments
The staged nature of off-plan payments creates multiple currency conversion events for non-euro buyers. Each stage payment represents an independent FX exposure. Using a specialist FX provider to forward-contract each payment tranche at or near reservation — locking in a known cost in your home currency — is straightforward and significantly reduces completion-cost uncertainty.
Rental Income, Resale and Exit — What Can Be Modelled for a Marbella New Build
What the Numbers Can and Cannot Tell You
No rental yield is published: no public dataset records achieved rents or closing prices for these homes. No appreciation or year-on-year figure exists for these addresses: it would need closing prices at two dates, and Spain publishes none. Anyone who quotes you a precise yield or a pre-completion appreciation percentage without a methodology behind it is either estimating or selling. What follows is a framework for forming your own view using verifiable inputs.
Gross vs. Net Yield: The Gap Matters
Gross yield — annual rental income divided by purchase price — is the number quoted in almost every investment pitch. Net yield, after deducting community fees, property management fees, maintenance reserves, IBI (local property tax), tourist licence costs, and periods of vacancy, is the number you will actually receive. In a premium new build in Marbella, the gap between gross and net is meaningful. Model both.
Tourist Licence Requirements
Short-term lettings in Andalucía require a Vivienda con Fines Turísticos (VFT) licence registered with the Junta de Andalucía. In some developments, particularly those with hotel-style management structures or within certain community statuses, tourist lettings are restricted or prohibited by the community statutes. Verify the community's position on tourist lettings before purchase if rental income is part of your investment case.
Liquidity and Exit
No days-on-market figure is published: no public record shows when a listing sold. The factors a future buyer will weigh are the ones you weigh today: zone, build quality, plot or terrace size, and the degree to which the property's specification has aged well.
Holding period: Off-plan buyers who sell within the construction period (assignment of contract, or cesión) avoid the full acquisition cost cycle but require developer consent and may face contractual restrictions.
Capital Gains Tax on Exit
A non-resident pays 19% on the gain from selling Spanish property, whatever the country of residence (Article 25.1.f of the IRNR law). The 19%/24% split applies to rent and deemed income, not to capital gains. When the seller is not resident in Spain, the buyer withholds 3% of the price and pays it to the tax agency on Modelo 211 within one month of the sale (Article 25.2 of the IRNR law; Article 14.3 of the IRNR Regulation). It is a payment on account of the seller's tax; only the excess over the tax due is refunded. Both should be factored into any exit strategy modelling.
Featured Listings: Three Developments in the Current Market
Three properties on the published register illustrate the upper end of the Marbella new build market. They are concrete reference points, not sales pitches; each page carries the current asking price.
7-Bedroom Villa, Nueva Andalucía (ZD-VISO1) A seven-bedroom villa in the Nueva Andalucía Golf Valley, for a buyer who wants golf-valley character with compound-grade scale.
8-Bedroom Villa, Benahavís (ZD-THH11) Eight bedrooms in Benahavís — the municipality that encompasses both La Zagaleta's private-estate market and a broader range of hillside developments.
8-Bedroom Villa, Benahavís (ZD-CORQ) Eight bedrooms, and among the more spatially generous developments in Benahavís. A property at this scale, in this location, is designed for a buyer for whom architecture and land position are the primary brief — not brand endorsement.
For a fuller view of current inventory, see the published register. The register is refreshed hourly. To match a development profile to your brief, describe it to Ask Muse, the AI search on this site, or write to the desk.